Home AI Technology Gaming Future Economy Geography Automobile Science Web Stories

The Dollar Is in 88% of Global Trades. Can Anything Replace It? – Future of the Dollar

Macro Discovery
On: September 11, 2026 6:34 AM
Follow Us:
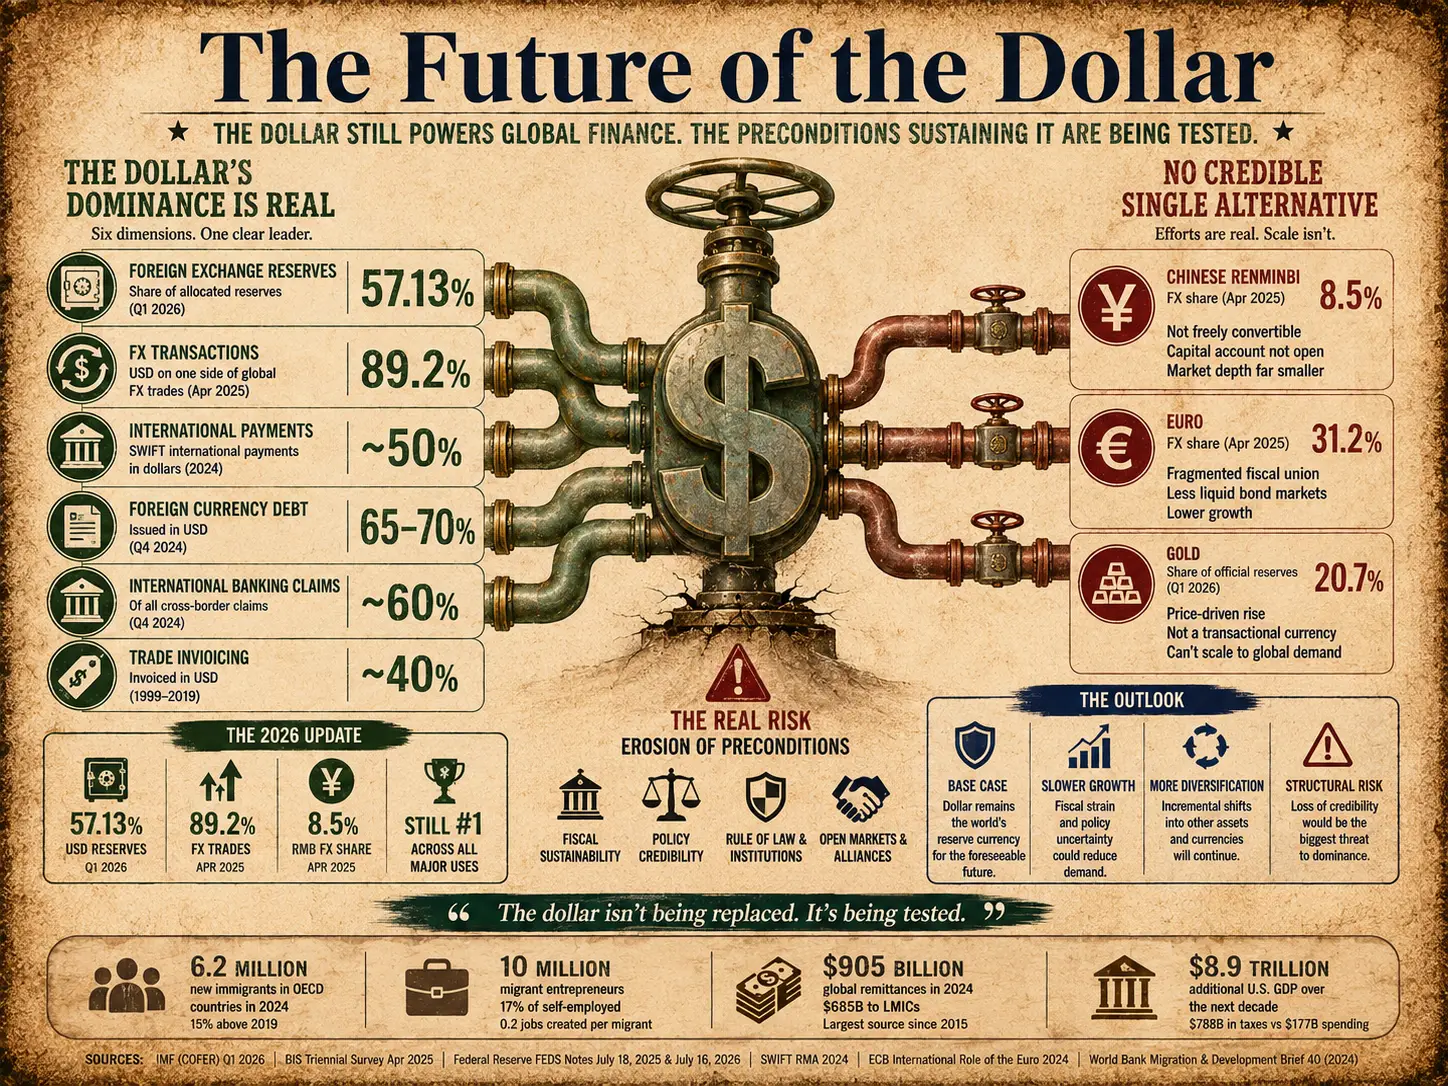
Vintage editorial infographic showing the future of the U.S. dollar through a central financial pipeline metaphor, highlighting dollar dominance in reserves, FX trading, payments and debt alongside the euro, Chinese renminbi and gold.
Charted: The Future of the Dollar — MacroDiscovery
MacroDiscovery
Currency · Global Finance · 6 min read · Federal Reserve 2025 Edition · Primary · Directly Fetched
Federal Reserve — “The International Role of the U.S. Dollar – 2025 Edition” (PRIMARY · federalreserve.gov · directly fetched · July 18, 2025 · DOI: doi.org/10.17016/2380-7172.3856 · Authors: Carol Bertaut, Bastian von Beschwitz, Stephanie Curcuru · Board of Governors of the Federal Reserve System) · IMF COFER Q2 2025 (PRIMARY) · Atlantic Council Dollar Dominance Monitor (March 9, 2026) · BIS Triennial Central Bank Survey 2022 (PRIMARY)
Currency · Global Finance · Reserve System · 2024–2025 Data

Charted: The Future
of the Dollar

The US dollar is still the world’s dominant currency across every major metric: 58% of global FX reserves, ~50% of SWIFT payments, 88% of all currency transactions, 60% of foreign currency debt. Its composite index “has remained in a narrow range between 65 to 70 since 2010.” But the DXY fell 10.7% in H1 2025 — the worst drop since 1973. Moody’s downgraded US debt. Tariffs have reduced openness to trade. The Federal Reserve itself notes its 2025 baseline “is not yet able to show any potential results” of these developments. The dollar’s dominance is real. The preconditions sustaining it are being tested.

By MacroDiscovery
Source: Federal Reserve FEDS Note (primary · directly fetched · July 18, 2025)
Key quote: “The dollar will likely remain the world’s dominant international currency for the foreseeable future.” — Federal Reserve 2025
58%
of global FX reserves in 2024 · “basically unchanged since 2022” · Euro 20% · Yen 6% · Pound 5% · RMB 2% · Federal Reserve 2025 (primary · directly fetched)
88%
of global FX transactions involve the dollar · “remained stable over the past 20 years” · BIS Triennial Survey 2022 (primary) · cited Fed 2025
~50%
SWIFT international payments in dollars · “has even slightly increased in recent years” · incl. intra-EU area: ~60% · Federal Reserve 2025 (primary)
10.7%
DXY fell in H1 2025 · worst drop since 1973 · but IMF COFER Q2 2025: 92% of reserve share decline was exchange-rate effect, not active reallocation · central banks held steady
Visualization 01 — The Dominance Dashboard · Dollar Share Across Six Key Metrics · 2024
The Dollar’s Six Dimensions of Dominance — None of Them Moving

The case for dollar dominance is not built on one number. It rests on six overlapping functions, each entrenching the others. These are the current readings across every major metric of global currency usage. Source: Federal Reserve — “The International Role of the U.S. Dollar – 2025 Edition” (PRIMARY · doi.org/10.17016/2380-7172.3856 · July 18, 2025 · directly fetched) · BIS Triennial Central Bank Survey 2022 (PRIMARY · FX transactions) · IMF COFER (PRIMARY · FX reserves).

FX Reserves
Central bank holdings · IMF COFER · 2024
USD 58%
FX Transactions
BIS 2022 Triennial Survey · “stable 20 years”
USD 88%
SWIFT Payments
Intl. payments · slightly increased · 2024
USD ~50%
Foreign Currency Debt
“Around 60% since 2010” · Fed 2025
USD 60%
Intl. Banking Claims
“55% claims / 60% liabilities” · Fed 2025
USD 55%
Trade Invoicing
Americas: 96% · Asia-Pac: 74% · ROW: 79%
USD 83% avg
US Dollar (USD)
Euro (EUR)
Other currencies
Note: FX transaction percentages sum to 200% (every transaction involves two currencies). Trade invoicing average shown (Americas 96% / Asia-Pac 74% / Rest of World 79%) weighted to a rough global average excluding Europe, where the euro dominates at 66%. Composite international currency usage index (weighted average of five measures): USD 65–70, Euro ~24, British pound ~6, Japanese yen ~7, Chinese renminbi ~3. Sources: Fed FEDS Note (primary · July 18, 2025) · BIS 2022 Triennial Survey · IMF COFER.
99%
Stablecoins dollar-linked
“About 99 percent of stable coin market capitalization is linked to the dollar.” Market cap: ~$220B (April 2025). “Crypto assets are de facto traded in dollars.” — Fed 2025
$1T+
Dollar banknotes held abroad
“Over $1 trillion in dollar banknotes were held by foreigners in Q1 2025, roughly half of total dollar banknotes outstanding.” — Fed 2025 primary
$9T
US Treasuries held by foreigners
“$9 trillion or 32% of marketable Treasury securities outstanding were held by foreign investors” as of Q1 2025 — “little changed since 2022” — Fed 2025 primary
Visualization 02A — The Long Decline · Reserve Share Trajectory 1995–2025
From 72% to 56%: The Slow Erosion — and Why Most of It Is Not Active De-Dollarization

The dollar’s share of global FX reserves has fallen from its 2001 peak of 72% to 56.32% in Q2 2025. But context matters at every stage of the decline. Sources: Federal Reserve (PRIMARY · directly fetched · July 18, 2025) · IMF COFER (PRIMARY) · IMF Q2 2025 COFER Report (PRIMARY).

~58%
Dollar’s approximate 1995 share of global reserves
The Fed notes the 2024 level “only returned to about the share it had in 1995.” This reframes the “decline” narrative: the dollar is back where it started before the tech boom inflated its share above historical norms.
1995
2001
72%
All-time peak — dollar’s highest reserve share in modern history
“The dollar share has declined from its peak of 72 percent of reserves in 2001, as foreign reserve managers have added to their portfolios a wide range of smaller currencies, including the Australian and Canadian dollars (IMF COFER).” — Fed 2025 primary verbatim. Reserve managers diversified into smaller currencies — not into a single rival.
66%
Dollar reserve share · gold share still below 10%
By 2015, dollar share had fallen 6 percentage points from its 2001 peak — primarily through diversification into the euro and smaller currencies. The Chinese renminbi, admitted to the IMF SDR basket in late 2015, was only beginning to appear in reserve allocations. Gold share: below 10% of official reserves.
2015
2022
58%
Russia sanctions · weaponization fears · no material reallocation
“Notably, it is basically unchanged since 2022, when it accounted for 58 percent of reserves, suggesting that U.S. sanctions on Russia following the invasion of Ukraine have not led to fears of dollar ‘weaponization’ causing a notable reallocation of reserves out of dollars.” — Fed 2025 primary verbatim. About three-quarters of foreign government holdings of safe US assets are held by countries with military ties to the United States (Weiss 2022).
58%
Annual 2024 official share · unchanged from 2022
“The U.S. dollar comprised 58 percent of disclosed global official foreign reserves in 2024 and far surpassed all other currencies including the euro (20 percent), Japanese yen (6 percent), British pound (5 percent), and the Chinese renminbi (2 percent).” — Fed 2025 primary verbatim. Gold share now over 23% — but this “mostly reflects the over 200 percent increase in the gold price.” Physical gold holdings rose only “less than 10 percent.”
2024
Q2 2025
56.32%
IMF COFER Q2 2025 · lowest since euro’s birth · but 92% = FX effects
IMF COFER Q2 2025 (primary): dollar reserve share fell from 57.79% to 56.32% in Q2 2025. But 92% of that decline was exchange-rate effects, not active portfolio reallocation. Adjusted for constant exchange rates: 57.67% — a decline of only 0.12 percentage points. The DXY fell 10.7% in H1 2025 — the worst half-year drop since 1973. Moody’s downgraded US government debt in 2025. The Fed notes its 2025 dataset cannot yet capture the impact of these developments.
Visualization 02B — The Challengers · Why Neither China Nor Europe Can Replace the Dollar Yet

The composite index of international currency usage, constructed by the Fed using five measures, places the dollar at 65–70, the euro at about 24, and the renminbi at only about 3. What are the specific barriers each challenger faces? Sources: Federal Reserve (PRIMARY · directly fetched · July 18, 2025) · Atlantic Council Dollar Dominance Monitor (March 9, 2026).

🇺🇸 US Dollar
65–70
58% of global FX reserves (2024, Fed primary)
88% of FX transactions (BIS 2022, stable 20 years)
~50% of SWIFT payments, “slightly increased”
99% of stablecoin market cap linked to dollar
$1T+ in banknotes held abroad (Q1 2025)
“Over half of countries” anchor currency to dollar
🇪🇺 Euro
~24
20% of global FX reserves (2024, Fed primary)
~22% of SWIFT payments (dominant within Europe)
Jointly-backed EU debt: $700B by May 2025
But: “small compared to over $28 trillion US Treasuries”
Political uncertainty from diverse eurozone members
ECB Lagarde May 2025: agenda for greater euro role
🇨🇳 Renminbi / RMB
~3
Only 2% of global FX reserves (2024, Fed primary)
“Not freely exchangeable, capital account not open”
“Investor confidence in Chinese institutions relatively low”
CIPS: 1,573 indirect + 193 direct participants
mBridge: $55.49B cumulative (Nov 2025) vs SWIFT trillions/day
“Effect has been rather limited thus far” — Fed 2025
🇯🇵 / 🇬🇧 Yen / Pound
~7 / ~6
Yen: 6% of global FX reserves (2024)
Pound: 5% of global FX reserves (2024)
Both issued by close US military allies — sanctions-aligned
No viable alternative for geopolitical adversaries seeking non-dollar reserve
“Geopolitical adversaries do not have many attractive alternatives to the dollar or the currencies of U.S. allies.” — Fed 2025

Every major measure of global currency usage tells the same story. The dollar is used in 88% of FX transactions. It anchors half of all SWIFT payments. It denominates 60% of all foreign currency debt outstanding. Its composite index — a weighted average of five measures — has remained between 65 and 70 since 2010. No other currency is close. And yet in 2025, the debate about the dollar’s future has intensified. The question is not whether the dollar is dominant. It clearly is. The question is whether the foundations of that dominance are eroding.

Federal Reserve — “The International Role of the U.S. Dollar – 2025 Edition” · PRIMARY · federalreserve.gov · directly fetched · July 18, 2025 · DOI: doi.org/10.17016/2380-7172.3856 · Authors: Bertaut, von Beschwitz, Curcuru
58%
“The U.S. dollar comprised 58 percent of disclosed global official foreign reserves in 2024 and far surpassed all other currencies including the euro (20 percent), Japanese yen (6 percent), British pound (5 percent), and the Chinese renminbi (2 percent).” — Fed 2025 primary verbatim
The dollar’s 58% reserve share in 2024 is simultaneously a record of decline and a record of endurance. It has fallen from 72% in 2001 — but the Fed’s own framing is clarifying: it “only returned to about the share it had in 1995.” The peak was an anomaly of the dot-com era, when US technology assets made dollar-denominated portfolios uniquely attractive. The return to 1995 levels is the normalization of an exceptional overshoot. More importantly: the dollar’s share has been “basically unchanged since 2022, when it accounted for 58 percent of reserves, suggesting that U.S. sanctions on Russia following the invasion of Ukraine have not led to fears of dollar ‘weaponization’ causing a notable reallocation of reserves out of dollars.” The most cited geopolitical threat to dollar dominance — that US sanctions would prompt a flight from dollar assets — has not materialized in the reserve data. The reason: most foreign holdings of safe US assets are in countries with military ties to the United States. Geopolitical adversaries have nowhere to go. Neither the renminbi (capital controls, trust deficit) nor gold (illiquid, yield-free) nor any other currency offers a credible alternative at scale.
Source: Federal Reserve — “The International Role of the U.S. Dollar – 2025 Edition” (PRIMARY · directly fetched · federalreserve.gov/econres/notes/feds-notes/the-international-role-of-the-u-s-dollar-2025-edition-20250718.html · July 18, 2025 · DOI: doi.org/10.17016/2380-7172.3856 · Authors: Carol Bertaut, Bastian von Beschwitz, Stephanie Curcuru · KEY VERBATIM: “the U.S. dollar comprised 58 percent of disclosed global official foreign reserves in 2024 and far surpassed all other currencies including the euro (20 percent), Japanese yen (6 percent), British pound (5 percent), and the Chinese renminbi (2 percent)” · “the dollar remains by far the dominant reserve currency and only returned to about the share it had in 1995” · “basically unchanged since 2022, when it accounted for 58 percent of reserves, suggesting that U.S. sanctions on Russia following the invasion of Ukraine have not led to fears of dollar ‘weaponization’ causing a notable reallocation of reserves out of dollars” · “The U.S. dollar share of international payments is about 50 percent and has even slightly increased in recent years. If intra-euro area payments are included, the dollar share is even higher at about 60 percent” · “the U.S. dollar was bought or sold in about 88 percent of global FX transactions in April 2022. This share has remained stable over the past 20 years” · “The dollar index level has remained in a narrow range between 65 to 70 since 2010, well ahead of all other currencies”)

“Absent any large-scale, lasting disruptions which damage the value of the U.S. dollar as a store of value or medium of exchange and simultaneously bolster the attractiveness of dollar alternatives, the dollar will likely remain the world’s dominant international currency for the foreseeable future.”

— Federal Reserve — “The International Role of the U.S. Dollar – 2025 Edition” (PRIMARY · directly fetched · federalreserve.gov · July 18, 2025 · DOI: doi.org/10.17016/2380-7172.3856)

Why Gold’s Rise Misleads — and What the Physical Numbers Actually Show

The headline that most concerns dollar watchers is not the reserve share — it is gold. The share of gold in official reserve assets “has more than doubled from below 10 percent in 2015 to over 23 percent now.” Central banks added 1,045 metric tons in 2024, the third consecutive year exceeding 1,000 metric tons. This looks like a flight from dollars. But the Fed’s own primary data reveals a critical nuance: this increase “mostly reflects the over 200 percent increase in the gold price over that period. In contrast, the physical quantity of gold holdings has only increased by less than 10 percent over this period.” Central banks are wealthier in gold because gold got more expensive — not because they systematically bought more of it. The Fed’s research further finds that “increases in gold holdings are generally not associated with a decline in U.S. dollar reserves except for China, Russia, and Turkey.” The gold story is mostly a price story. The de-dollarization interpretation requires more evidence than central bank balance sheets currently provide.

Why it matters: the gold price surge has created a statistical artefact that makes reserve diversification look more dramatic than it is. Most central banks — including in Japan and India — have not significantly increased physical gold holdings. Those that have (Russia, China, Turkey) are acting for geopolitical reasons that don’t apply to the 149 economies tracked in IMF COFER.
Federal Reserve 2025 (PRIMARY · directly fetched) + Atlantic Council Dollar Dominance Monitor (March 9, 2026) + IMF COFER Q2 2025 (PRIMARY)
88%
“The U.S. dollar was bought or sold in about 88 percent of global FX transactions in April 2022. This share has remained stable over the past 20 years.” — Fed 2025 primary verbatim (BIS 2022 Triennial Survey). SWIFT payments: “about 50 percent and has even slightly increased in recent years.”
The 88% FX transaction figure is perhaps the single most striking number in dollar dominance data — and also the most underappreciated. Reserves are what central banks hold on their balance sheets. FX transactions are what the global private market actually uses to buy and sell everything. Every time a Korean electronics manufacturer pays a Taiwanese semiconductor supplier, both are likely using dollars. The dollar is the global vehicle currency: even two non-dollar currencies are often exchanged through the dollar because dollar markets are deeper and cheaper than any bilateral cross-currency pair. This is the “medium of exchange” role — and it is nearly impervious to the forces driving reserve diversification. Even if central banks slowly reduce dollar reserves, the private market will keep using dollars for as long as dollar liquidity is unmatched. The 88% figure has not moved meaningfully in two decades. The SWIFT data tells the same story: the dollar share of international payments is “about 50 percent and has even slightly increased in recent years.” The narrative of a dollar in retreat from transactional dominance is not supported by any primary data source.
Source: Federal Reserve (PRIMARY · directly fetched · July 18, 2025 · verbatim: “the U.S. dollar was bought or sold in about 88 percent of global FX transactions in April 2022. This share has remained stable over the past 20 years” · “The U.S. dollar share of international payments is about 50 percent and has even slightly increased in recent years. If intra-euro area payments are included, the dollar share is even higher at about 60 percent” · citing BIS 2022 Triennial Central Bank Survey) · Atlantic Council Dollar Dominance Monitor (March 9, 2026 · CIPS: 1,573 indirect + 193 direct participants · mBridge: $55.49B cumulative volume by November 2025 · “Trump’s trade policies are causing more countries to signal their intent to diversify from the dollar” · “A large-scale sale of US assets remains unlikely given the depth of US markets and the lack of viable alternatives”) · IMF COFER Q2 2025 (PRIMARY · 56.32% share · “92% of that decline was driven by exchange-rate effects, not central bank portfolio changes” · DXY −10.7% H1 2025)

The Real Risk Is Not Replacement — It Is the Erosion of the Preconditions

The Federal Reserve’s 2025 note contains a critical caveat. It states explicitly that it “is not yet able to show any potential results of the change in the U.S. credit rating or changes to tariff rates in 2025. Rather, it provides a baseline for where the international role of the dollar stood before these announcements.” Moody’s downgraded US government debt in 2025. Tariffs reduced US openness to trade. The DXY fell 10.7% in H1 2025 — the worst drop since 1973. None of this has yet shown up in the reserve and transaction data. But the Fed identifies what would create long-term risk: damage to the dollar’s role as a store of value OR medium of exchange, combined with a simultaneous bolstering of alternatives. The first condition requires sustained policy erosion of US fiscal credibility. The second condition requires China to open its capital account — which it has not done. Neither condition is close to being met. But both are more plausible in 2026 than they were in 2020. The dollar faces no credible replacement. It faces credibility risk.

Why it matters: dollar dominance is not a natural law. It rests on specific preconditions: US fiscal credibility, open capital flows, rule of law, and the depth of US financial markets. These have been the most stable features of the US economy for 80 years. The question of the dollar’s future is ultimately a question about the durability of those preconditions under stress.
Federal Reserve 2025 (PRIMARY · directly fetched) — Challenges Section · also: Moody’s US downgrade 2025 · DXY data H1 2025
~3
The renminbi’s composite index of international currency usage: only about 3 out of 70 for the dollar. “The renminbi is not freely exchangeable, the Chinese capital account is not open, and investor confidence in Chinese institutions is relatively low.” — Fed 2025 primary verbatim. “Their effect has been rather limited thus far.”
The renminbi challenge to dollar dominance is real in China’s bilateral relationships — China now conducts approximately 53% of its own trade in yuan, and mBridge (the CBDC-based cross-border settlement system) reached $55.49 billion in cumulative volume by November 2025 (Atlantic Council). But these are drops in the bucket of global finance. SWIFT clears trillions of dollars daily. The BIS estimates $7.5 trillion in daily FX transactions. The renminbi’s absence from freely convertible international markets — a deliberate policy choice by Beijing, not an accident — means it cannot perform the primary function of a reserve currency: being available to any holder who needs to liquidate it into other assets at any time, in any amount, without restrictions. The Fed notes that “geopolitical adversaries do not have many attractive alternatives to the dollar or the currencies of U.S. allies.” Even Russia, which has made the most aggressive push to de-dollarize its economy since 2022, has found the renminbi’s capital controls to be a substantial constraint. For the EU euro: jointly-backed EU debt reached $700 billion by May 2025 — “a large amount for the EU” but “small compared to the over $28 trillion of U.S. Treasuries outstanding.” No single EU government debt instrument provides the safe haven depth that US Treasuries offer. Until it does, the euro’s reserve role will remain regional rather than global.
Source: Federal Reserve (PRIMARY · directly fetched · July 18, 2025 · verbatim: “the renminbi is not freely exchangeable, the Chinese capital account is not open, and investor confidence in Chinese institutions is relatively low. These factors all make the Chinese renminbi relatively unattractive for international investors” · “China has recently increased various efforts to promote international use of the renminbi, but their effect has been rather limited thus far” · “the EU started to issue an unprecedented amount of jointly-backed debt, which reached about $700 billion by May 2025. While this is a large amount for the EU, it is small compared to the over $28 trillion of U.S. Treasuries outstanding” · “geopolitical adversaries do not have many attractive alternatives to the dollar or the currencies of U.S. allies” · “about 99 percent of stable coin market capitalization is linked to the dollar, implying that crypto assets are de facto traded in dollars” · “By April 2025, the total market capitalization of dollar stablecoins had reached about $220 billion” · “the share of gold in official reserve assets has more than doubled from below 10 percent in 2015 to over 23 percent now. However, this increase mostly reflects the over 200 percent increase in the gold price over that period. In contrast, the physical quantity of gold holdings has only increased by less than 10 percent” · “absent any large-scale, lasting disruptions…the dollar will likely remain the world’s dominant international currency for the foreseeable future”) · Atlantic Council Dollar Dominance Monitor (March 9, 2026 · CIPS: 1,573 indirect + 193 direct participants · mBridge: $55.49B cumulative)
Key Numbers at a Glance
FX Reserves · Annual 2024
58%
Dollar share of global FX reserves — “basically unchanged since 2022.” Euro 20%, Yen 6%, Pound 5%, RMB 2%. Down from 72% peak in 2001 — but “only returned to about the share it had in 1995.”
Fed (PRIMARY · directly fetched)
FX Transactions · BIS 2022
88%
Dollar bought or sold in 88% of all FX transactions globally — “remained stable over the past 20 years.” The most stable and striking number in all dollar dominance data.
Fed (PRIMARY · citing BIS 2022)
Stablecoins · April 2025
99%
Of all stablecoin market cap linked to the dollar. $220B total cap by April 2025. “Crypto assets are de facto traded in dollars.” Stablecoins may cause more EM economies to become “effectively dollarized.”
Fed (PRIMARY · directly fetched)
Composite Index · RMB vs USD
3 vs 70
Renminbi composite usage index ~3 vs dollar 65–70. Not freely exchangeable. Capital account not open. Trust deficit. “Effect has been rather limited thus far.” mBridge: $55B cumulative vs SWIFT’s daily trillions.
Fed (PRIMARY · directly fetched)
Frequently Asked Questions
Is the US dollar losing its reserve currency status?
The dollar’s share of global FX reserves has declined from its 2001 peak of 72% to 58% in 2024 — but the Federal Reserve’s 2025 primary analysis (directly fetched, July 18, 2025) notes it “only returned to about the share it had in 1995” and is “basically unchanged since 2022.” The more important indicators are transactional: the dollar is involved in 88% of all FX transactions globally (stable for 20 years) and represents ~50% of SWIFT payments (“slightly increased in recent years”). Its composite usage index has stayed in a narrow range of 65–70 since 2010. The dollar is not losing its reserve status. It is normalising from an exceptional peak, while its transactional dominance remains essentially intact.
Will China’s renminbi replace the US dollar?
Not in the foreseeable future, according to every primary data source. The renminbi accounts for only 2% of global FX reserves (2024) and has a composite international currency usage index of about 3 — compared to the dollar’s 65–70. The Federal Reserve (2025 primary) identifies the core obstacles: “the renminbi is not freely exchangeable, the Chinese capital account is not open, and investor confidence in Chinese institutions is relatively low.” China’s Cross-Border Interbank Payment System (CIPS) has 1,573 indirect and 193 direct participants, and the mBridge CBDC settlement system reached $55.49 billion in cumulative volume by November 2025 — but SWIFT clears far more in a single day. The Fed concludes China’s efforts to internationalise the renminbi have had an effect that “has been rather limited thus far.”
Did Russia’s Ukraine invasion trigger a flight from the dollar?
No — at least not in the reserve data available through 2024. The Federal Reserve’s 2025 primary analysis states directly: the dollar’s reserve share is “basically unchanged since 2022, when it accounted for 58 percent of reserves, suggesting that U.S. sanctions on Russia following the invasion of Ukraine have not led to fears of dollar ‘weaponization’ causing a notable reallocation of reserves out of dollars.” The reason: about three-quarters of foreign government holdings of safe US assets are held by countries with military ties to the United States. Geopolitical adversaries seeking alternatives face a fundamental problem: the alternative reserve currencies (euro, pound, yen) are issued by the same US-allied countries that imposed sanctions on Russia. The renminbi has capital controls. There is no credible flight destination.
What is the dollar’s share of global trade invoicing?
The dollar dominates trade invoicing in every region except Europe. According to Fed primary data (2025, citing Boz et al. 2020 and IMF data): 96% of trade invoicing in the Americas, 74% in the Asia-Pacific region, and 79% in the rest of the world. The only exception is Europe, where the euro dominates at 66%. This means that when a Japanese company buys Australian resources, it likely transacts in dollars — even though neither party is American. The dollar is the “vehicle currency” of global trade: all roads go through it, not because of US trade volume, but because dollar liquidity is unmatched in every market on earth.
What is the biggest long-term risk to dollar dominance?
The Federal Reserve’s own 2025 analysis identifies the risk precisely: damage to the dollar’s role as a store of value or medium of exchange combined with a simultaneous bolstering of the attractiveness of alternatives. Neither condition is close to being met — but both are more plausible after 2025 than before. The note acknowledges it “is not yet able to show any potential results of the change in the U.S. credit rating [Moody’s 2025 downgrade] or changes to tariff rates in 2025.” US fiscal sustainability (gross national debt $38T+, annual interest approaching $1T) is the primary long-run threat. The tariff-driven reduction in US trade openness is a secondary risk. If US fiscal credibility erodes while eurozone fiscal integration deepens — jointly-backed EU debt grew to $700B by May 2025 — conditions for a gradual euro role expansion could slowly improve. But the transition would take decades, not years.
Sources
  • Federal Reserve — “The International Role of the U.S. Dollar – 2025 Edition” (PRIMARY · directly fetched · federalreserve.gov/econres/notes/feds-notes/the-international-role-of-the-u-s-dollar-2025-edition-20250718.html · July 18, 2025 · DOI: doi.org/10.17016/2380-7172.3856 · Authors: Carol Bertaut, Bastian von Beschwitz, Stephanie Curcuru · Board of Governors of the Federal Reserve System · KEY VERBATIM: “the U.S. dollar comprised 58 percent of disclosed global official foreign reserves in 2024 and far surpassed all other currencies including the euro (20 percent), Japanese yen (6 percent), British pound (5 percent), and the Chinese renminbi (2 percent)” · “declined from its peak of 72 percent of reserves in 2001” · “only returned to about the share it had in 1995” · “basically unchanged since 2022, when it accounted for 58 percent of reserves, suggesting that U.S. sanctions on Russia following the invasion of Ukraine have not led to fears of dollar ‘weaponization’ causing a notable reallocation of reserves out of dollars” · “The U.S. dollar share of international payments is about 50 percent and has even slightly increased in recent years. If intra-euro area payments are included, the dollar share is even higher at about 60 percent” · “the U.S. dollar was bought or sold in about 88 percent of global FX transactions in April 2022. This share has remained stable over the past 20 years” · “about 55 percent of international and foreign currency claims and 60 percent of liabilities are denominated in dollars” · “share of foreign currency debt denominated in dollars has remained around 60 percent since 2010” · “dollar accounted for 96 percent of trade invoicing in the Americas, 74 percent in the Asia-Pacific region, and 79 percent in the rest of the world” · “The dollar index level has remained in a narrow range between 65 to 70 since 2010” · “over $1 trillion in dollar banknotes were held by foreigners in the first quarter of 2025” · “By April 2025, the total market capitalization of dollar stablecoins had reached about $220 billion” · “99 percent of stable coin market capitalization is linked to the dollar” · “$9 trillion or 32 percent of marketable Treasury securities outstanding were held by foreign investors” [Q1 2025] · “the share of gold in official reserve assets has more than doubled from below 10 percent in 2015 to over 23 percent now. However, this increase mostly reflects the over 200 percent increase in the gold price over that period. In contrast, the physical quantity of gold holdings has only increased by less than 10 percent over this period” · “the renminbi is not freely exchangeable, the Chinese capital account is not open, and investor confidence in Chinese institutions is relatively low” · “China has recently increased various efforts to promote international use of the renminbi, but their effect has been rather limited thus far” · “$700 billion by May 2025. While this is a large amount for the EU, it is small compared to the over $28 trillion of U.S. Treasuries outstanding” · “geopolitical adversaries do not have many attractive alternatives to the dollar or the currencies of U.S. allies” · “this note is not yet able to show any potential results of the change in the U.S. credit rating or changes to tariff rates in 2025” · “absent any large-scale, lasting disruptions which damage the value of the U.S. dollar as a store of value or medium of exchange and simultaneously bolster the attractiveness of dollar alternatives, the dollar will likely remain the world’s dominant international currency for the foreseeable future”)
  • IMF COFER — Currency Composition of Official Foreign Exchange Reserves (PRIMARY · data.imf.org · Q2 2025 latest report · 149 economies · 56.32% dollar share Q2 2025 · down from 57.79% Q1 2025 · 92% of decline = exchange-rate effects not portfolio changes · constant exchange rate adjusted: 57.67% · note: “Starting in 2025Q3, with revisions back to 2000Q1, the IMF eliminated the ‘unallocated’ portion of the COFER dataset” · DXY fell 10.7% in H1 2025 driving the apparent decline)
  • BIS — Triennial Central Bank Survey 2022 (PRIMARY · bis.org · April 2022 survey · dollar bought or sold in 88% of global FX transactions · “has remained stable over the past 20 years” · euro: 31% [sum to 200%] · next survey due 2025)
  • Atlantic Council — Dollar Dominance Monitor (March 9, 2026 · atlanticcouncil.org · CIPS: 1,573 indirect participants and 193 direct participants · mBridge cumulative transaction volume: $55.49B by November 2025 · “Trump’s trade policies are causing more countries to signal their intent to diversify from the dollar” · “A large-scale sale of US assets remains unlikely given the depth of US markets and the lack of viable alternatives” · “over the medium to long term, continued instability could encourage more countries to gradually reduce their holdings of US assets”)
  • MDPI — “De-Dollarization of Central Bank Reserves in the World Economy: 2015–2025” (peer-reviewed · published March 7, 2026 · “global USD share falls from 66% to 56%” over 2015-2025 · “nearly one percentage point per year on average” · “dollar share in SWIFT payments has also remained remarkably stable within the range of 40 to 50%” citing Bertaut et al. 2025 · physical gold accumulation: Russia 915 mt, China 538 mt, India 322 mt · “no structural decline in the dominance of the dollar”)
  • Moody’s — US government debt credit rating downgrade (2025 · ratings.moodys.com/ratings-news/443154 · cited in Federal Reserve 2025 primary as a development whose impact cannot yet be shown in available data)
Macro Discovery

Sukh Dhaliwal

Sukh Dhaliwal is the founder of Macro Discovery, an independent digital publication covering AI, technology, science, future trends, and global innovation through visual storytelling and data-driven analysis.

Join WhatsApp

Join Now

Join Facebook

Follow us

Leave a Comment