Industries Pricing a 2030 Recession
The industries already pricing in a 2030 recession. The prices say the slump is booked.
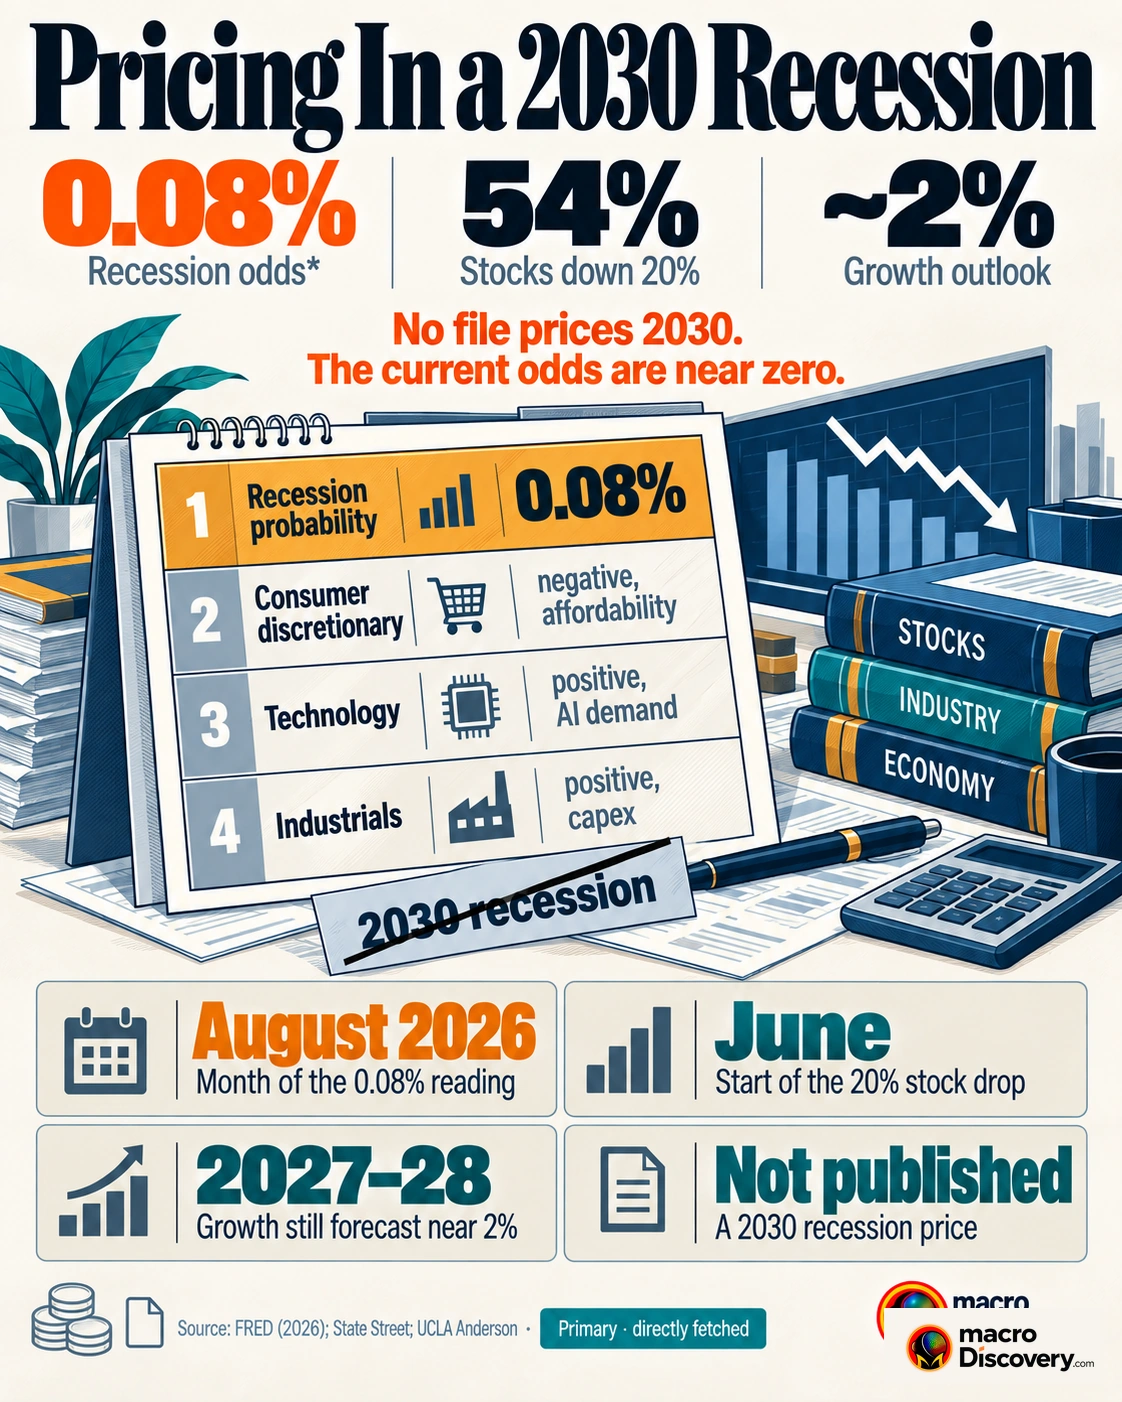
There is no ranking. Official forecasts still show growth. The freight slump already ended. The 2030 line is an AI-payback risk, not a price.
Three numbers
- 3.3% — IMF forecast for global growth in 2026, the same pace as 2025. 2027 is 3.2%. Source: IMF.
- 2022 to 2024 — the freight recession. By late 2026 rates were rising because capacity had left. Source: AlixPartners.
- $1.1 trillion — hyperscaler capital-spending plans for 2027, revised up. Source: State Street, sector note.
What the data shows
A common claim is that industries are already pricing a 2030 recession, and that a ranking of them shows the slump is booked. The fact is that there is no such ranking, and the official forecasts are still rises. The IMF’s latest World Economic Outlook update put global growth at 3.3% in 2026, up 0.2 point from its prior estimate, and even with 2025. It put 2027 at 3.2%. US growth was forecast at 2.4% in 2026. A recession is a fall in output. These numbers are not a fall. A list of industries that have priced 2030 would need a price, a date, and a volume. The headline has the date and not the other two.
The industry that did have a recession already had it. Freight’s downturn ran from 2022 to 2024, called the worst in decades. By October 2026, analysts said the recession was over and rates were climbing because carriers had exited, fleets had shrunk, and equipment orders had slowed. Spot rates had moved above contract rates for the first time since early 2022. Carrier guidance was being raised, not cut. A past slump from too many trucks is not a 2030 price. It is a capacity hole that takes years to refill.
The 2030 line that does exist is a conditional note about AI payback. Apollo’s chief economist wrote that if free cash flow at the large cloud firms disappoints, spending already committed could squeeze margins and pressure the stock index, and that this could tip the economy into recession. That is an if. State Street’s fourth-quarter 2026 sector note said hyperscaler capital-spending plans for 2027 had been revised up, toward $1.1 trillion, and that cloud revenue growth was expected to accelerate. Spending more is the opposite of pricing a slump. A risk note and a capex raise can sit in the same month. Only one of them is a price.
A risk note about AI payback is not a booked recession. Capex plans for 2027 were revised up.
| Count | Figure | What it is |
|---|---|---|
| Global growth, 2026 | 3.3% | IMF. Same pace as 2025 |
| Global growth, 2027 | 3.2% | Not a fall |
| US growth, 2026 | 2.4% | IMF |
| Freight recession | 2022–2024 | Over. Rates up on thin capacity |
| Cloud capex, 2027 | $1.1 trillion | Plans revised up |
How it was measured
A growth forecast is a projected change in output. A recession in the usual statistical sense is a decline. Pricing a recession would mean futures, freight contracts, or earnings guidance that assume a fall in 2030. The IMF numbers assume a rise. Carrier guidance in late 2026 was being raised.
A risk note is a conditional sentence. Apollo’s line says if cash flow disappoints, then margins and the index could suffer. It does not say 2030 output has been marked down. Capex plans are company budgets. A budget revised up is more spending, not less.
What it means
It is settled that the IMF forecasts 3.3% global growth in 2026, that the freight recession of 2022 to 2024 is described as over, and that 2027 cloud spending plans were revised up. It is not settled that any industry has priced a 2030 recession. Use 3.3% for the growth forecast. Use 2022 to 2024 for the freight slump. Use $1.1 trillion for the spending plans. Do not rank industries on a recession that is not in the forecast.
Common misreadings
- A 3.3% growth forecast is not a booked recession.
- The freight slump already happened. Rates are up because trucks left, not because 2030 was priced.
- An if-then note on AI payback is not a price. Capex plans were revised up.
Where the numbers come from
How we built this
- Dataset: IMF growth update; AlixPartners freight note; State Street sector note and Apollo risk note.
- Scope: Forecasts and prices. No industry ranking, because no 2030 recession price was published.
- Figures: 3.3% is the 2026 growth forecast. 2022 to 2024 is the freight slump. $1.1 trillion is planned cloud spending. The ranking is treated as empty.