The Economics of Oil
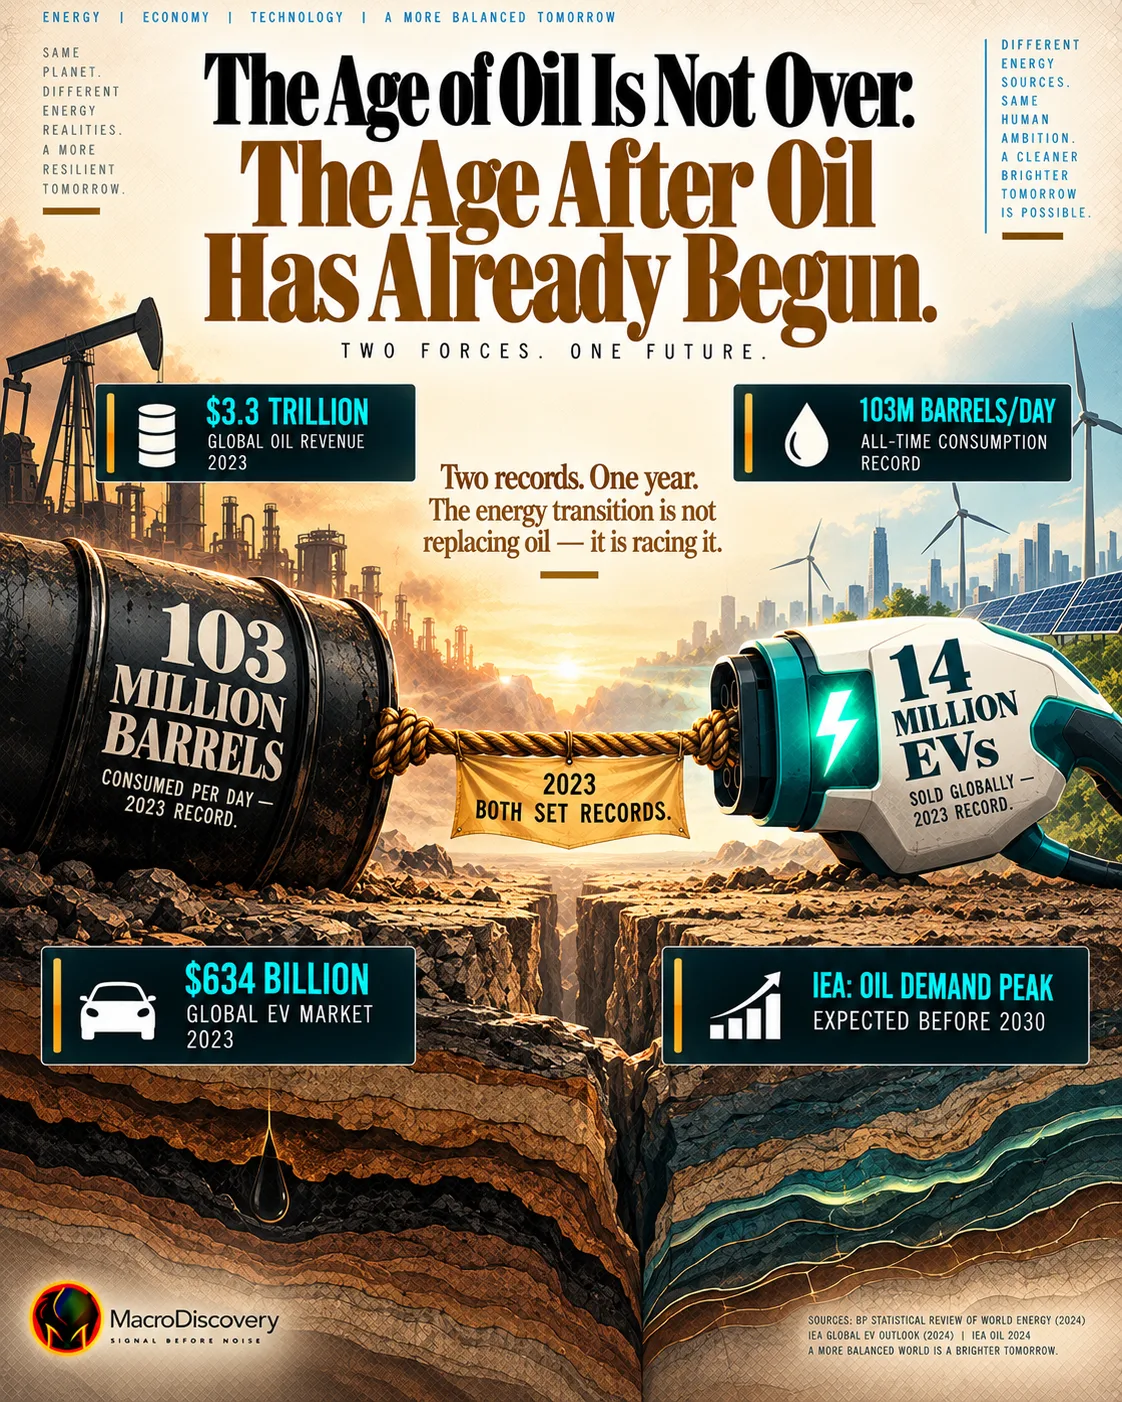
The world burned about 104 million barrels a day in 2025 — higher than 2023. It also bought more than 20 million electric cars. Both sentences are true. They are not a paradox. They are two markets.
Oil is still jet fuel, plastics, trucks and Asia. EVs are a slice of the passenger-car fleet. 2026 demand forecasts split because the Gulf is a war risk, not because the EV lot emptied the barrel.
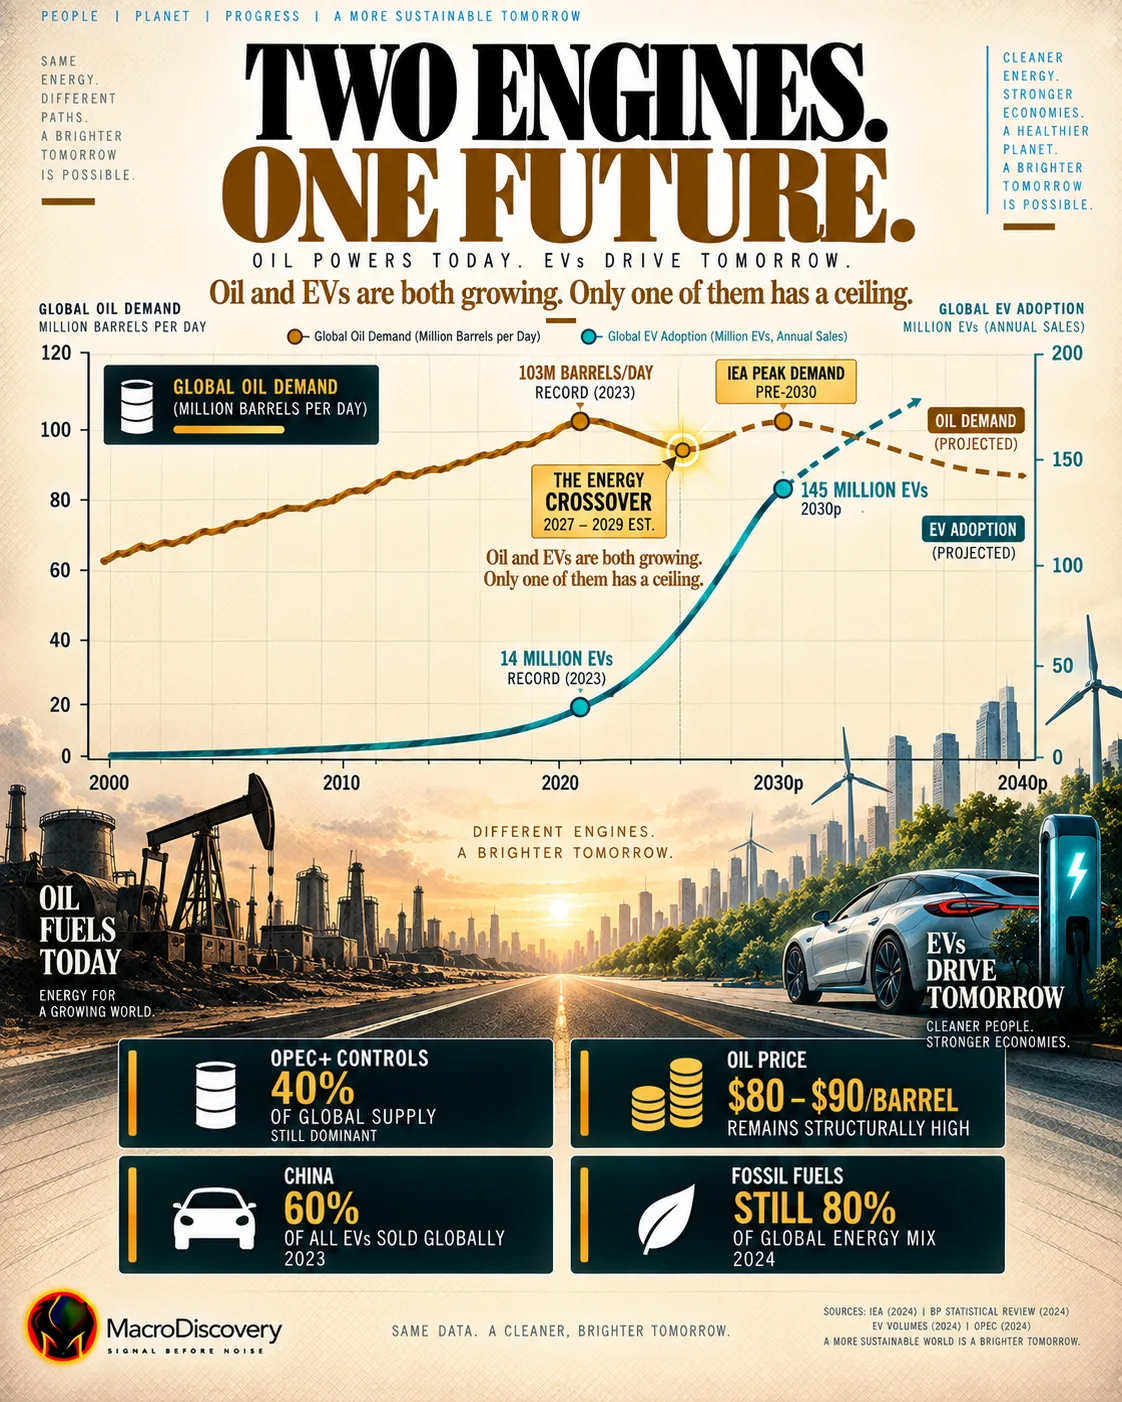
The subtitle froze 2023. That year did set a then-record. It did not stay the record. IEA Oil Market Report tables put world demand at about 103.6 million barrels a day in 2024 and 104.4 million in 2025. Call 2025 the latest full-year high in that vintage. 2026 is a fight: some IEA months have demand falling because Gulf flows and prices broke, not because the car park went electric overnight.
The other half of the line held. The Global EV Outlook 2026 says electric-car sales grew about 20% in 2025 to more than 20 million — a quarter of new cars worldwide. The agency’s 2026 base case is about 23 million, near 28% of sales. Records on both sides of the garage.
A barrel and a battery in the same year
- —2024103.6
- —2025104.4
- —2023 postcardretired
2026 IEA monthly reports have swung with the Gulf. Treat in-year 2026 as a forecast war, not a settled annual bar.
Cars are not the whole barrel
Passenger cars are one slice of oil. Diesel trucks, ships, jets, petrochemicals and power in some grids still drink. Non-OECD Asia still adds barrels even as Europe’s gasoline fades. An EV displaces gasoline in a rich-city fleet. It does not delete naphtha bound for a cracker in China. That is why 20 million electric cars and 104 million barrels can share a calendar.
IEA OMR vintage
Higher than 2024. 2023 is not the last peak.
2025 · GEO 2026
25% of new cars. 2026 case: ~23 million / 28%.
Demand + EVs
Largest oil buyer among the giants. Largest EV market.
Gulf risk
IEA demand cuts this year are disruption, not peak-oil theory.
Peak oil demand is a date people keep moving. Peak EV headlines are a sales chart. 2025 printed both. That is the economics of oil right now: the barrel has more jobs than one drivetrain.Macro Discovery reading of IEA OMR and GEO 2026
The 2023 caption froze a moving market.
Writers liked 2023 because it was the first clean post-Covid high that arrived in the same breath as EV records. Two more years of demand growth made the caption lazy. The interesting fact is not “record plus record.” It is that oil’s growth is now a petrochemical-and-Asia story while the West’s gasoline story is flattening. EVs are eating the easy barrel. The hard barrels remain.
2026 will tempt a new caption — “demand fell, EVs won.” Only if you skip the footnote that IEA’s 2026 cuts are tied to a Gulf shock and product shortages. A war-year dip is not a structural peak. Wait for a quiet year before you write the obituary.
Editorial reading of IEA June 2026 OMR demand table and GEO 2026 sales. The IEA did not write this box. 2026 annual demand is still a forecast.If you remember two things
~104.4 mb/d. Not a 2023 freeze-frame.
2024 was already 103.6. The postcard year is retired.
20 million+ electric cars in 2025
A quarter of new cars. They do not drink jet fuel or naphtha.
Short answers
One demand table. One EV sales book.
- Oil: IEA Oil Market Report demand table — world 2024 103.58 mb/d, 2025 104.41 mb/d. 2023 treated as a prior record, not current peak.
- EVs: IEA Global EV Outlook 2026 — >20 million electric-car sales in 2025 (25% of new cars); 2026 case ~23 million / ~28%.
- 2026 oil: labeled as an unsettled forecast amid Gulf risk. Not used as an annual bar.